Introducing the Debt Center: a living debt snowball inside your budget
Your credit cards and loans are already in EnvelopeBudget. The new Debt Center turns them into a snowball or avalanche plan with a debt-free date, what-if projections, history, and a printable progress poster.

Most debt payoff tools ask you to type in every balance, then come back each month and type them in again. The plan drifts out of date the moment a statement closes, and the tracker slowly turns into one more chore.
EnvelopeBudget already knows what you owe. Your credit cards and loans are accounts, every payment is a transfer you can see, and the balance is the ledger. So the new Debt Center builds the payoff plan from that data instead of asking you to copy it somewhere else.
Open it from the sidebar, under Calendar.
Your debts, already enrolled
Every open credit card, loan, or line of credit account in your budget shows up in the Debt Center automatically. The balance is the account balance. When a payment lands in the ledger, the plan updates.
Each debt keeps a few details the ledger does not know: APR, minimum payment, an optional planned payment, and a due day. Enter those once and the Debt Center flags anything still missing. Credit cards can use a calculated minimum (2% or $25, the American Express and Discover variants, or your own formula) so the projection tracks how card minimums actually shrink.
Debts that are not accounts in your budget, such as a mortgage you track elsewhere or a loan from family, can be added manually with their own balance and payment log.
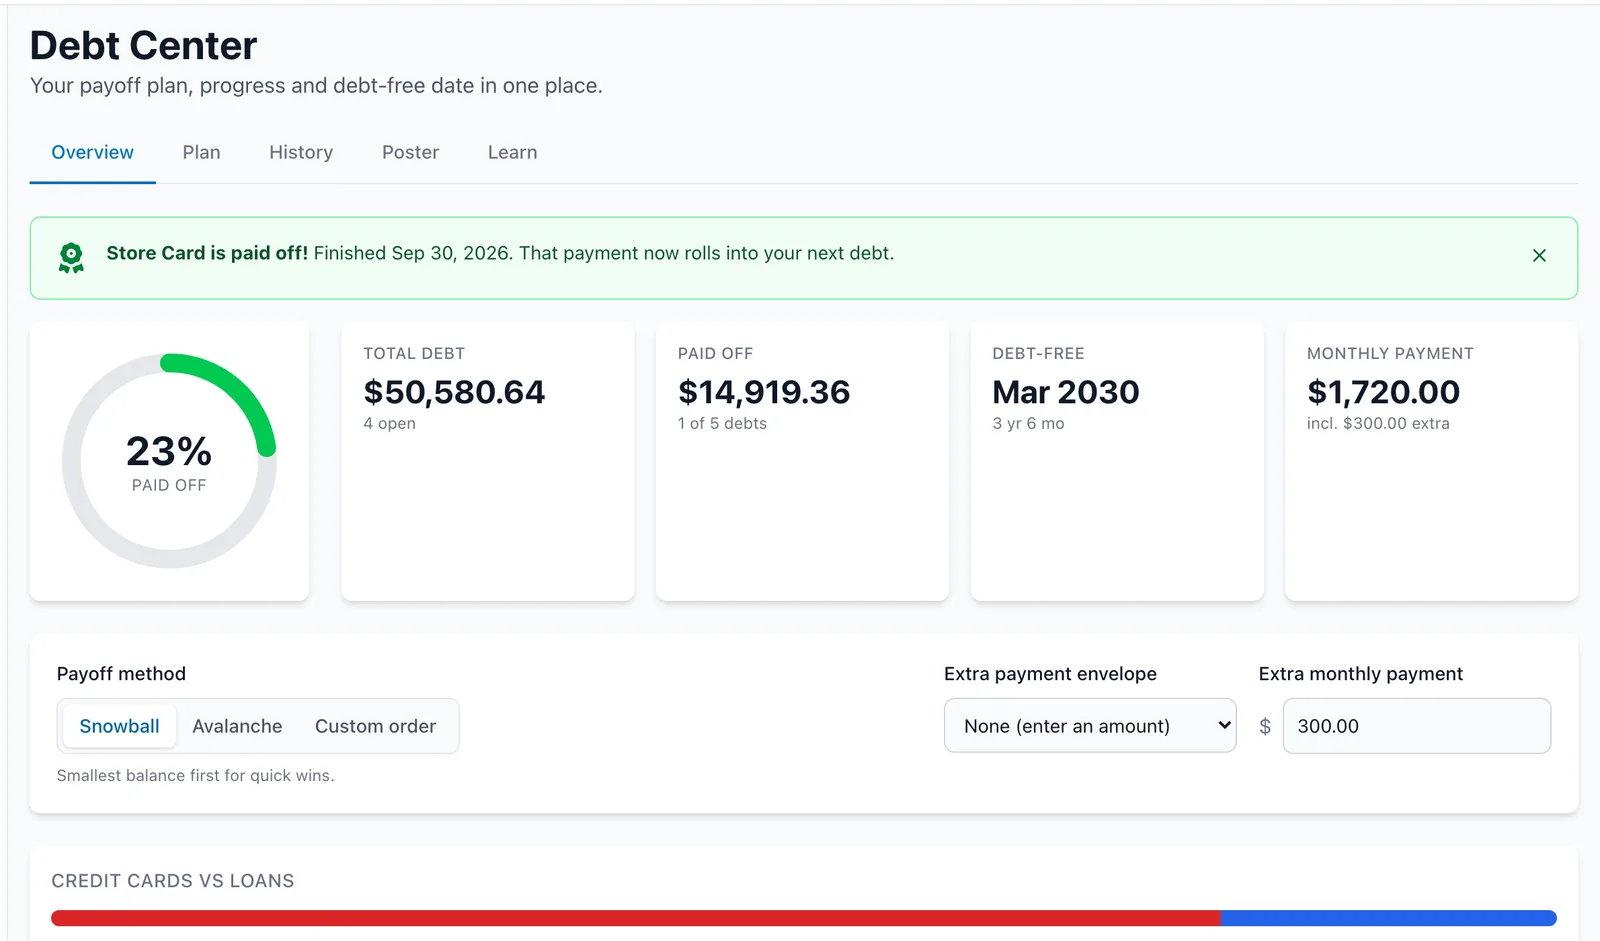
Snowball, avalanche, or your own order
Pick a method at the top of the page and the payoff order reshuffles:
- Snowball attacks the smallest balance first for quick wins.
- Avalanche attacks the highest interest rate first to save the most money.
- Custom order lets you drag debts into whatever order keeps you motivated.
The debt at the front of the line is marked Attack now. Everything after it is queued with a "next up" position. When a debt is paid off, its payment rolls into the next one. That rollover is what makes a snowball a snowball, and the projection models it month by month.
The extra monthly payment is a plan setting, and it can follow an envelope. Point it at a "Debt Snowball" envelope and the plan uses whatever you allocate to that envelope each month. Fund more, and the debt-free date moves closer. This is the piece a standalone tracker cannot do: the payoff plan and the budget that pays for it are the same thing.
A debt-free date you can push around
The Plan tab shows the debt-free date, months to go, total interest, and a stacked chart of every balance falling to zero. Below it, a what-if panel lets you try a different method, a larger extra payment, or a one-time payment today, and the numbers and chart respond as you type.
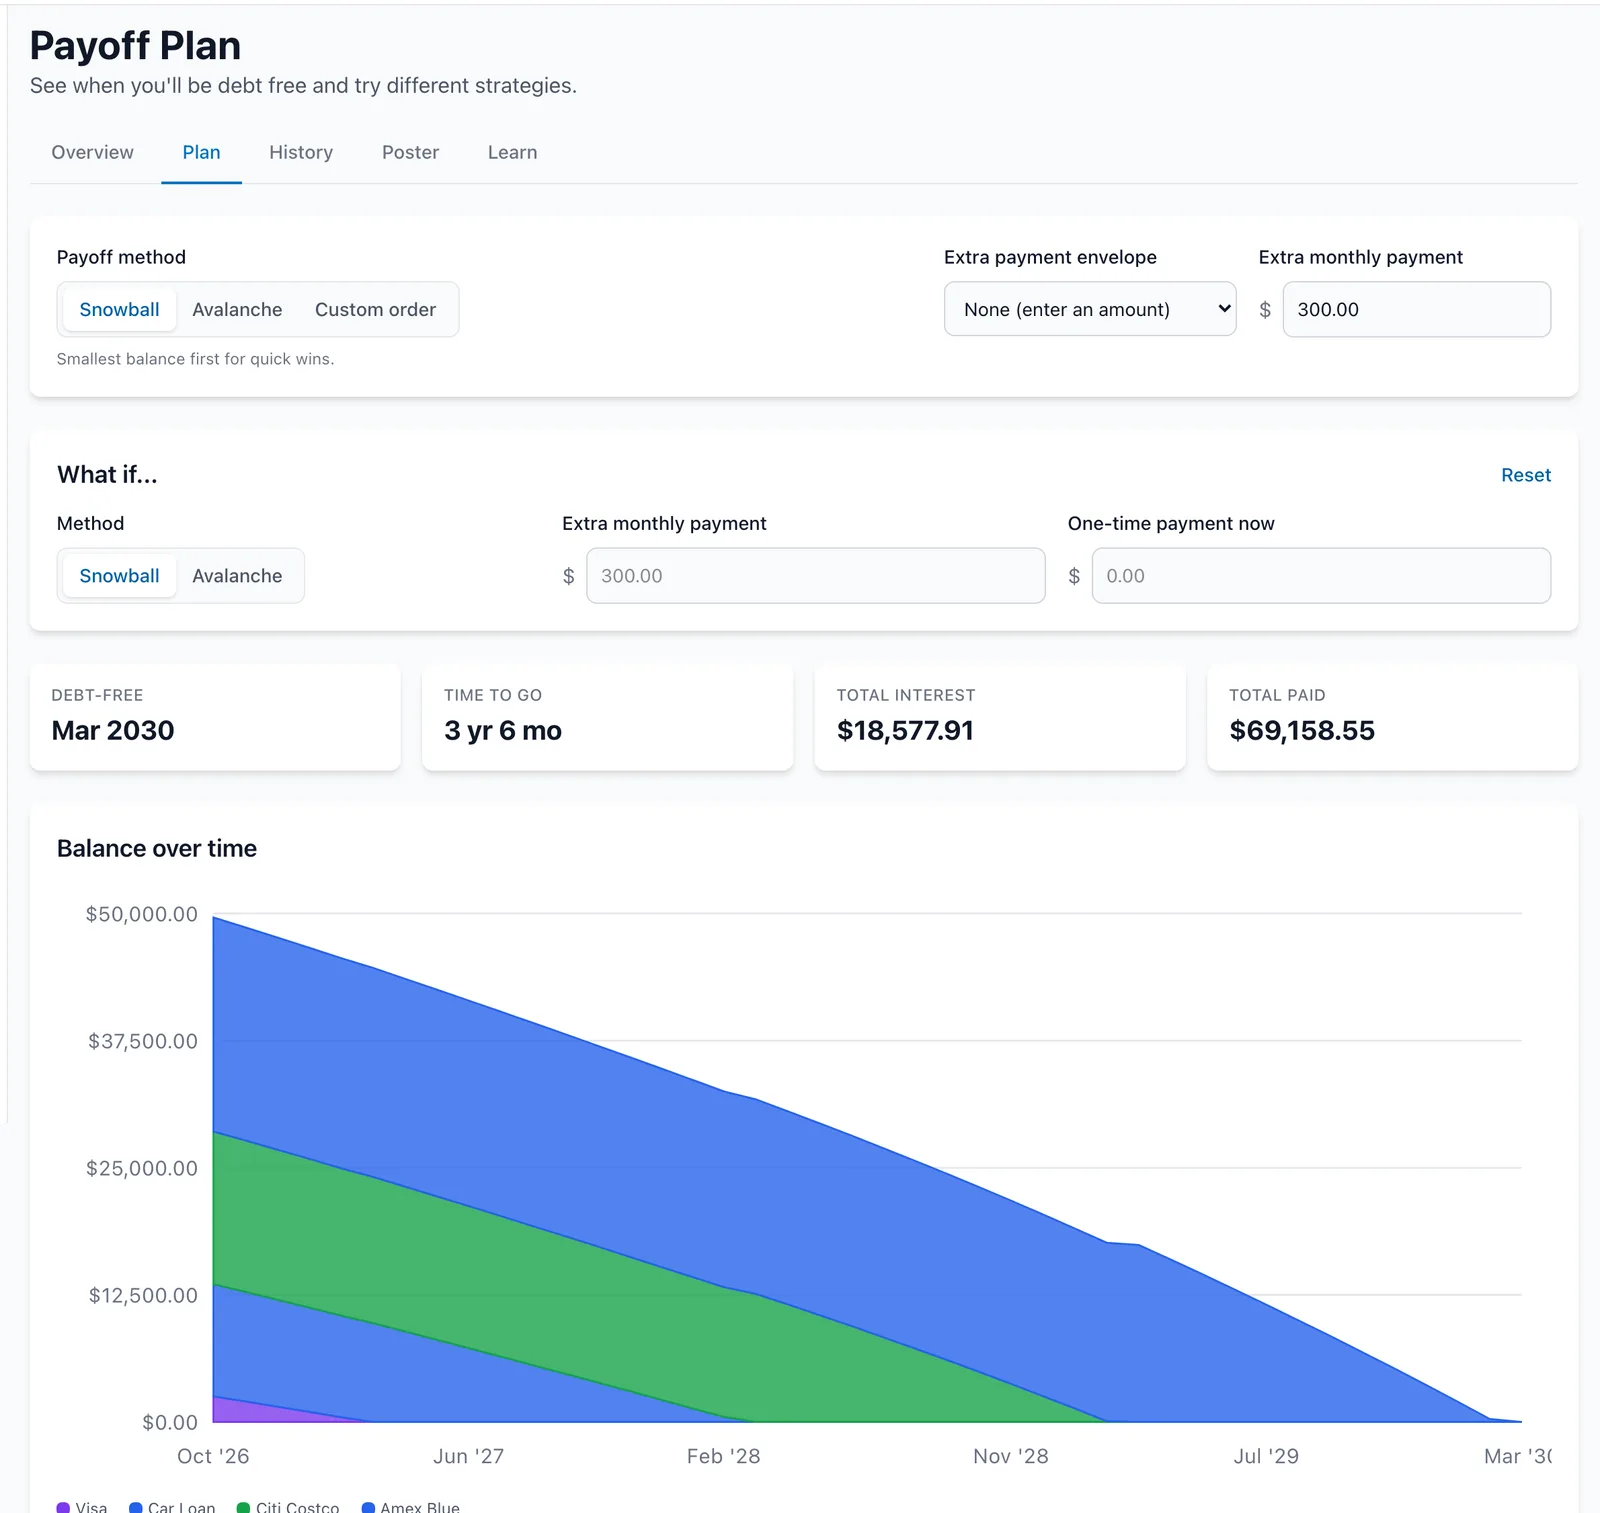
The comparison table puts snowball, avalanche, and minimums-only side by side: when each one gets you to zero, how much interest each one costs, and how much you save over paying minimums. If a minimum payment is lower than the monthly interest, the table says so instead of pretending the debt will ever end.
Progress that starts from the right number
Percent paid is measured against the larger of a debt's starting balance and the highest balance it has ever reached. For a loan, enter the original amount and progress is measured from there. For a credit card, the peak balance rises whenever you charge more than you pay, so progress sits at 0% until the card genuinely starts coming down. A card at its all-time high never gets credit for progress it has not made.
Every debt card also shows its last payment, with the date and amount, pulled straight from the ledger.
History, breakdown, and a poster for the fridge
History walks your ledger backwards to show month-end balances, payments, and interest charges for each debt over the last 6 to 60 months. The credit cards vs loans breakdown on the overview shows how much of your debt is revolving and how much is installment, with totals per type.
The Poster tab prints a one-page progress poster: a thermometer for total progress, a checklist of debts to cross off as they fall, and milestone markers at 10, 25, 50, 75, 90, and 100 percent plus one for each debt paid off. Print it, put it on the fridge, and check a box when the next one goes.
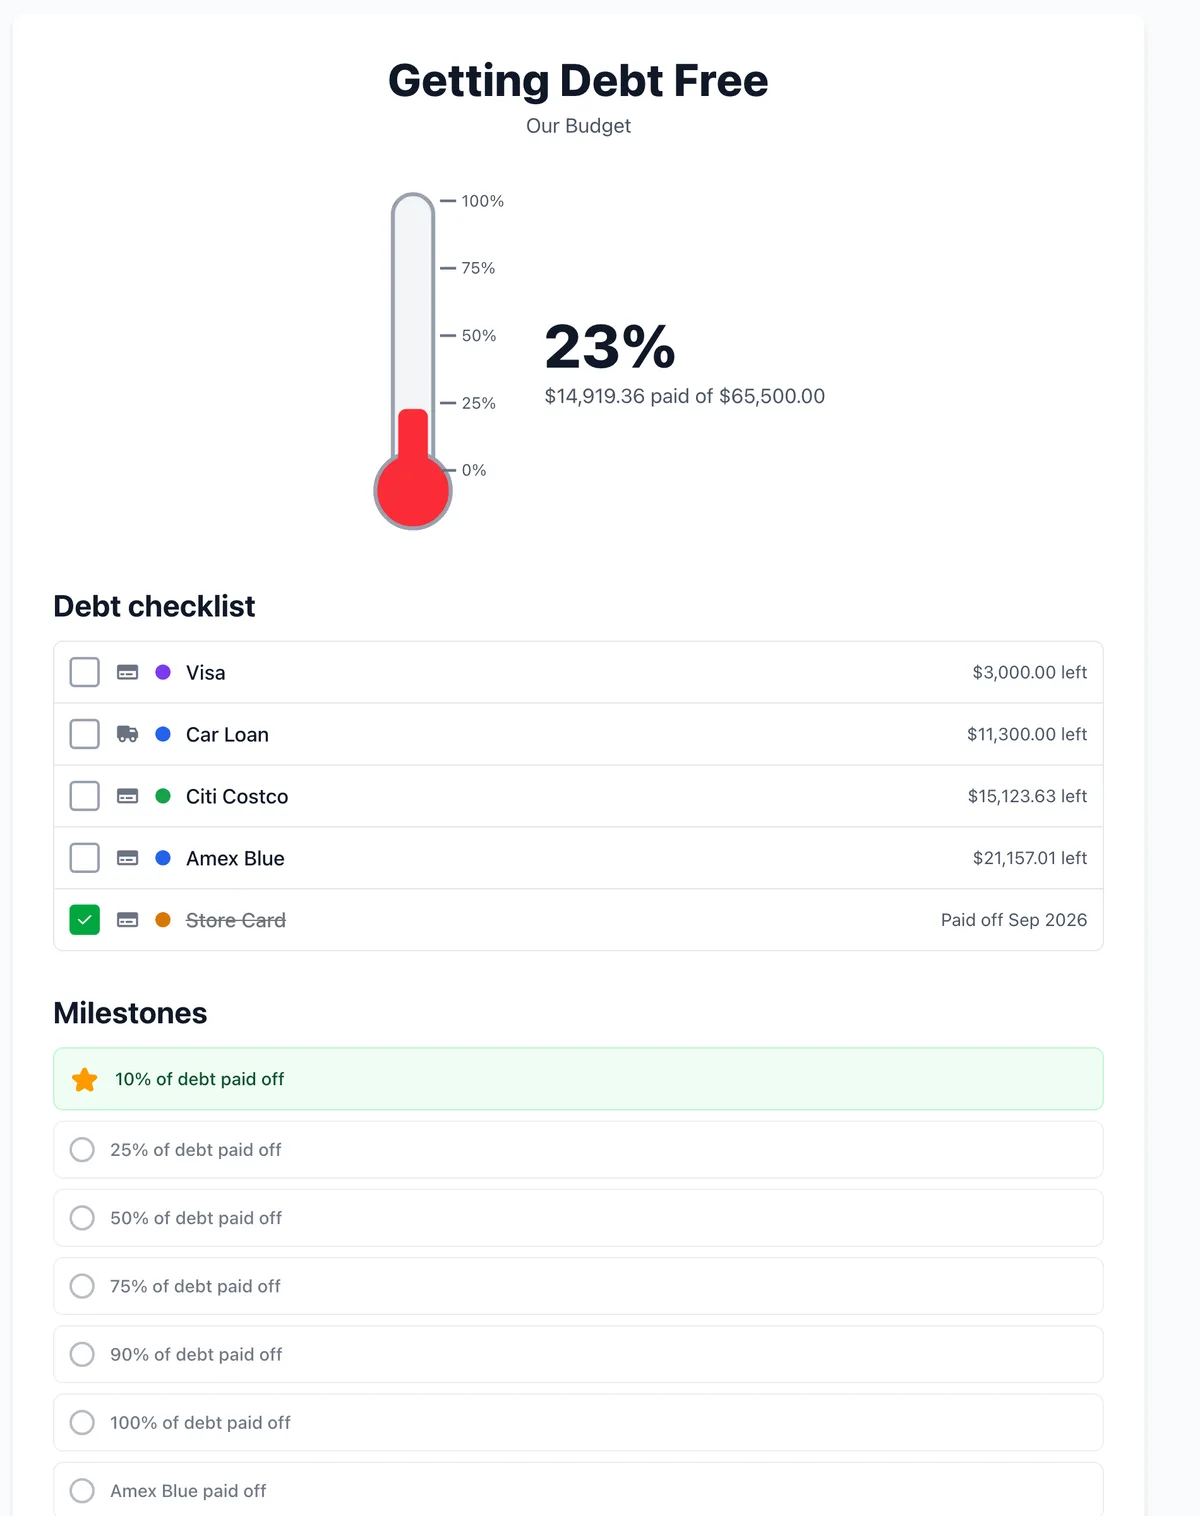
When a debt hits zero, the overview celebrates it and reminds you that its payment now rolls into the next debt.
For AI assistants too
If you use the EnvelopeBudget MCP server, two read-only tools expose the debt plan and a payoff projection, so a connected assistant can answer questions like "what happens to my debt-free date if I add $200 a month?" without you copying numbers into a chat.
Snowball or avalanche?
If you are deciding between methods, Debt Snowball vs Avalanche covers the trade-off, and How to Get Out of Debt with Envelope Budgeting walks through the whole approach. The Debt Center is included in every EnvelopeBudget plan. Open it from the sidebar, fill in the APR and minimum on each card, and see your date.